Political conference speeches tend to contain plenty of promises, plenty of applause and, quite often, policies that won’t actually affect us for several years.
Prime Minister Andy Burnham’s first Labour conference speech contained a number of announcements that could eventually have implications for household finances and Financial Planning. However, the important word there is eventually.
Perhaps the biggest announcement concerned the State Pension. Currently, the Triple Lock means it increases each year by the highest of inflation, average earnings growth or 2.5%. Under the Government’s proposals, from April 2030 the link to earnings would be removed, creating what has been described as a “Double Lock” based on inflation or 2.5%.
Nothing changes during this Parliament, and the Prime Minister also said that pensioners relying on lower incomes would not be “dragged into paying Income Tax” during that period.
The longer-term significance is worth watching, though. For anyone planning for a Retirement that could last 20, 30 or even 40 years, relatively small changes to the way the State Pension increases can become much more meaningful over time. It’s another reminder that a good Retirement Plan shouldn’t rely too heavily on today’s rules remaining unchanged forever.
There was also a major announcement on social care. The Government intends to create a National Care Service for England from the next Parliament, which would be free at the point of use and designed to reduce the risk of families having to use their homes and savings to meet care costs. The detail, including exactly how it would be funded, is still to come, so there’s little value in changing any later-life or Estate Planning on the strength of the announcement alone.
Elsewhere, the Prime Minister announced proposed reforms to leasehold, changes to Right to Buy and plans intended to reduce household energy costs. There were also commitments around AI, youth employment, electoral reform and the UK’s future relationship with the EU.
It’s a lot to digest, but from a Financial Planning perspective our message is much simpler: don’t confuse an announcement with a rule change.
Governments regularly set out policies that take years to develop, and the final legislation can look quite different from the original proposal. Making significant decisions about your Pension, Investments, Estate or Retirement based on what might happen several years from now can therefore create more problems than it solves.
That doesn’t mean we ignore what’s happening. Quite the opposite. Part of good Financial Planning is looking ahead, understanding what may be coming and considering whether a plan remains resilient if the rules change.
For now, however, most of these announcements belong firmly in the “keep watching, don’t start changing things yet” category.
With the Budget approaching later this month, we’ll continue separating the things that make good headlines from the things that genuinely affect your Financial Plan.
After several months of speculation about where interest rates might go next, the Bank of England has decided that, for now at least, the best course of action is to do nothing.
At its September meeting, the Bank held the Base Rate at 3.75% for the sixth consecutive time, although the decision wasn’t unanimous. Six members voted to keep rates unchanged, while three wanted an increase to 4%.
The reason for the caution is inflation. UK inflation rose to 3.1% in August, moving further above the Bank’s 2% target, with higher energy costs contributing to the increase. The Bank currently expects inflation to rise further before easing again, although, as we’ve learned over recent years, economic forecasts have an unfortunate habit of changing as the world around them changes.
For the moment, the Bank appears to be balancing two competing risks. Raising rates could help if inflation becomes more persistent, but higher borrowing costs also affect households and businesses and can slow the wider economy. Holding rates therefore gives policymakers more time to understand whether the latest increase in inflation is temporary or becoming more embedded.
For the rest of us, there’s a useful Financial Planning lesson in all of this. We can spend an enormous amount of time trying to predict where interest rates will go next. Savers may wonder whether to fix their money before rates fall, while borrowers might question whether they should wait in the hope that cheaper Mortgage deals are around the corner.
The difficulty is that nobody knows with certainty what happens next, including the people setting the rates.
That’s why decisions around Cash, Mortgages and Investments should ideally be based on what you’re trying to achieve and when you’ll need the money, rather than a prediction about the Bank of England’s next move.
For Savers, current rates remain considerably healthier than the near-zero returns we became accustomed to for many years, although it’s still important to consider the impact of inflation and Tax on the real return you’re receiving. For anyone approaching the end of a Fixed-rate Mortgage, it’s sensible to start exploring the options early rather than relying on rates moving in a particular direction before your existing deal ends.
The Bank’s next decision will come in November, and no doubt there’ll be plenty of predictions before then. We’ll keep watching what happens. Your Financial Plan, however, shouldn’t need to guess correctly.
It must be nearly Budget time, because the rumours about what the Chancellor might change are already arriving thick and fast.
With John Healey’s first Budget due on 28th October, Pensions, Tax-Free Cash, Capital Gains Tax and Inheritance Tax are all finding their way into the speculation. Some of those rumours may ultimately prove correct, but if previous Budgets have taught us anything, it’s that plenty won’t.
The problem isn’t the speculation itself. It’s what people sometimes do because of it.
Tax-Free Cash from Pensions is a good example. Once again, there is speculation about whether the current rules could change, which understandably leaves some people wondering whether they should take their Tax-Free Cash now, just in case.
But withdrawing money from a Pension is a significant Financial decision and isn’t always straightforward to reverse. Depending on how benefits are accessed and what subsequently happens to the money, there can be implications for Tax, future Pension contributions and your wider Retirement Plan.
The same principle applies elsewhere. Selling Investments early because Capital Gains Tax might change, making gifts earlier than planned or entering into complicated Inheritance Tax arrangements purely because of a Budget rumour can all have consequences long after the original headline has disappeared.
There are, of course, some changes we already know about. Most unused Pension funds are due to come within the scope of Inheritance Tax from April 2027, while frozen Tax thresholds continue to have an impact as incomes and Pensions rise. Those are things we can plan around because we have something concrete to work with, although even confirmed future legislation can evolve before implementation.
And that’s really the distinction that matters. Good Financial Planning prepares for change without trying to predict every change.
There may be perfectly sensible planning to complete before a Budget, particularly where allowances are available or something already needs attention. One simple example is checking that your Pension beneficiary nominations are up to date. But any decision should make sense for you whether or not the Chancellor subsequently makes the change everyone was predicting.
So, between now and 28th October, expect plenty more headlines telling us what could, might or may happen.
We’ll keep watching them. For most people, however, the best Budget preparation may still be a cup of tea, a little patience and waiting to make important Financial decisions based on what the Chancellor actually says.
Capital Gains Tax has just had a record-breaking year, although it’s probably not a record many taxpayers will be celebrating.
HMRC figures show that CGT liabilities reached £24.2 billion in the 2024/25 Tax Year, an increase of 89% on the previous year. The number of individuals paying the Tax also jumped by 44% to 551,000.
Some of that increase came from people with very substantial gains. In fact, just 8,000 individuals with gains of £2 million or more accounted for 58% of the total Tax due.
But there’s another part of the story that’s particularly relevant for Financial Planning.
The CGT Annual Exempt Amount, effectively the amount of gain you can realise before CGT may become payable, has fallen significantly over recent years and was reduced to just £3,000 for 2024/25. That means people don’t necessarily need enormous Investment portfolios or second properties before Capital Gains Tax becomes something they need to think about.
At the same time, CGT rates have changed, and speculation ahead of the October 2024 Budget encouraged some investors to sell assets earlier than they otherwise might have done. Residential property disposals attracting CGT also increased significantly during the year.
All of this highlights why Tax Planning is increasingly about lots of small decisions made over time, rather than one clever decision made at the end.
Making appropriate use of ISAs and Pensions, considering when gains are realised and making use of available allowances can all form part of a longer-term Financial Plan. Depending on individual circumstances, spreading disposals across different Tax Years may also be more appropriate than selling everything at once.
Of course, Tax shouldn’t be the only reason for holding or selling an Investment. Sometimes there are perfectly good reasons to realise a gain and pay the Tax. The aim of Financial Planning isn’t to avoid Tax at all costs, but to make sure you’re not paying more than you reasonably need to simply because opportunities to plan ahead were missed.
With another Budget approaching, Capital Gains Tax is once again appearing in the speculation about what the Chancellor might change next. We’ll find out soon enough whether anything actually does.
In the meantime, the record £24.2 billion collected last year provides a useful reminder that good Tax Planning rarely starts with the Tax bill. It starts much earlier.
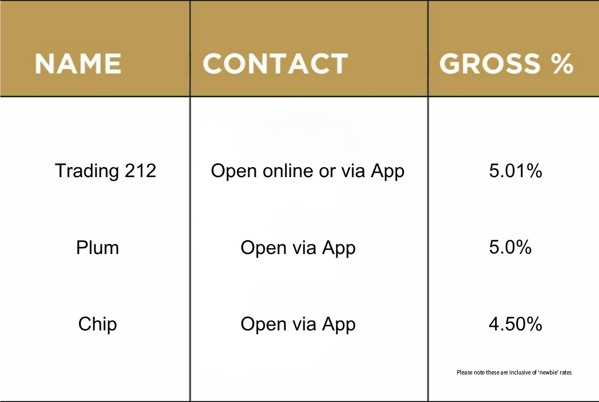
Please check the terms and conditions before opening any account. If in doubt, consult with your financial adviser directly, as the above is for your information only.
Source: Moneysavingexpert.com 30/09/2026
Penguin © 2026. Penguin is a trading name of Penguin Wealth Planners Ltd. who are authorised and regulated by the Financial Conduct Authority (FCA no. 830057). For further information please View More
 Customer Focus Award